
Blog
Insights from PCF practice
Studies, analyses and experience from projects with industrial companies.Articles are currently available in German only.
Articles are currently available in German only.
With the introduction of new regulations such as the Corporate Sustainability Reporting Directive (CSRD) , carbon accounting and thus the disclosure of CO2 emissions are becoming increasingly important for companies.
The distinction between the Corporate Carbon Footprint (CCF) and the Product Carbon Footprint (PCF) plays a central role.
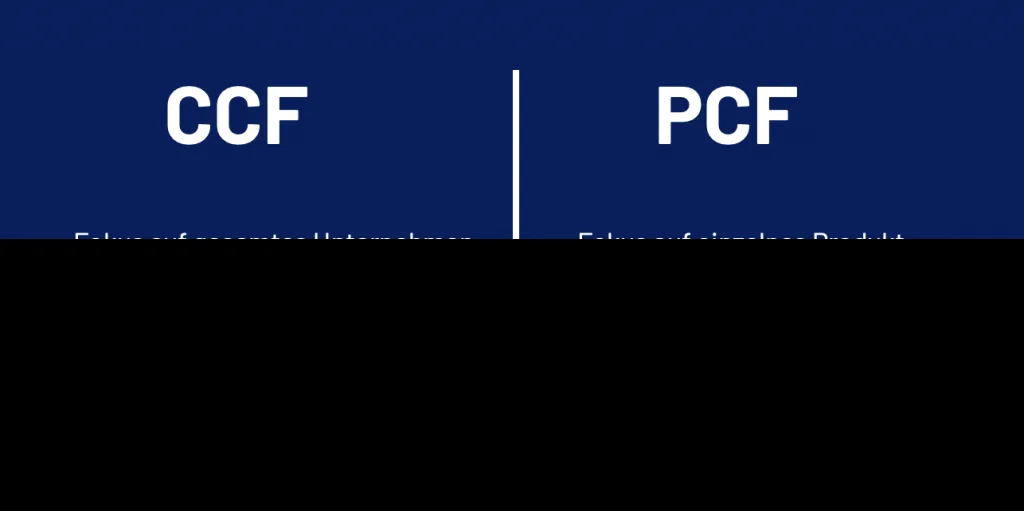
The Corporate Carbon Footprint (CCF) shows a company’s total CO2 emissions over a certain period. In contrast, the Product Carbon Footprint (PCF) focuses on assessing the environmental impact of a specific product across its entire life cycle, from raw material extraction through manufacturing, transport and use to disposal.
Given the complex requirements and different approaches to measuring emissions, it is becoming crucial for companies to understand both perspectives and integrate them into their reporting.
What is the Corporate Carbon Footprint?
The EU has set ambitious climate targets and increasingly demands transparency from companies regarding their sustainability and climate performance. This is being driven by the Corporate Sustainability Reporting Directive (CSRD), which requires companies to disclose climate-related information. The Corporate Carbon Footprint (CCF) is an integral part of this disclosure, as it shows the CO2 footprint of the entire company. Calculating it can help find emission sources in the company and thus enable targeted emission reduction measures.
The CSRD uses European reporting standards known as the European Sustainability Reporting Standards (ESRS). The climate standard (ESRS E1) specifies which climate-related information must be disclosed as part of the Corporate Carbon Footprint (CCF), including detailed figures on emissions in Scopes 1 and 2 and the relevant Scope 3 categories (upstream & downstream). Further information on the scopes in carbon accounting can be found in our article on the GHG Protocol.
From 1 January 2024, public-interest entities with more than 500 employees are obliged to disclose sustainability-related information in accordance with the CSRD. In future, other large companies, listed small and medium-sized enterprises (SMEs) and companies from third countries will also be subject to this reporting obligation. According to estimates by the Accounting Standards Committee of Germany (DRSC), the number of companies subject to reporting in Germany is expected to rise from around 500 to about 15,000 by 2027.
But companies outside the CSRD reporting obligation must also expect more requests from their customers or suppliers for climate-related figures. Recording the Corporate Carbon Footprint (CCF) can help answer such requests. If an overall calculation of all relevant emissions of a company is not yet possible, a calculation at product level (PCF) can help create internal and external transparency.
Which standards must be considered when calculating the Corporate Carbon Footprint?
Companies have various standards available for calculating the Corporate Carbon Footprint (CCF). The Greenhouse Gas Protocol Corporate Accounting and Reporting Standard is the most widely used. ISO 14064-1 also contains principles and requirements for calculating and reporting greenhouse gas emissions at company level.
In principle, both standards can be used to meet the CSRD requirements. However, companies that opt for ISO 14064-1 must meet some reporting requirements of the Greenhouse Gas Protocol, for example regarding system boundaries and the disclosure of Scope 2 emissions. There is therefore much to be said for choosing the Greenhouse Gas Protocol as the accounting standard.
Telusio’s view
Since the CSRD was amended last year at the latest, Scope 3 emissions have increasingly come into focus alongside Scope 1 and 2. However, many companies face a challenge here, as data is often only available to a limited extent.
To approximate total Scope 3 emissions, it makes sense to calculate the emissions in Scope 3.1 (purchased goods and services), as these often account for the majority of emissions. Calculating emissions at product level (PCF) can be used for this.
Your customer is asking for a PCF?Let’s talk.
Discover the easiest way to audit-ready PCFs – AI-powered and expert-reviewed.
Book an initial call