
Blog
Insights from PCF practice
Studies, analyses and experience from projects with industrial companies.Articles are currently available in German only.
Articles are currently available in German only.
Methods and frameworks for CO2 accounting are a crucial mechanism for ensuring that real greenhouse gas savings are achieved.
– Definition according to ScienceDirect after Slade et al., 2018
Carbon or greenhouse gas accounting comprises a variety of methods for calculating the carbon dioxide emissions of a company or country.
Carbon accounting can help disclose the emissions footprint of a company and its products. This allows companies to comply with legal requirements, advance their own sustainability strategy and meet customer wishes.
For companies, producing quantifiable information about their emissions footprint can be extremely complex. International accounting standards such as the GHG Protocol or ISO 14064 / ISO 14067 provide companies with a framework for accurate and efficient carbon accounting and help avoid “greenwashing”.
How can a company quantify its emissions footprint using carbon accounting?
Carbon accounting is a complex topic, partly because of the different ways of quantifying CO2 emissions. A distinction is made between physical (“activity-based”) and financial (“spend-based”) carbon accounting.
Spend-based
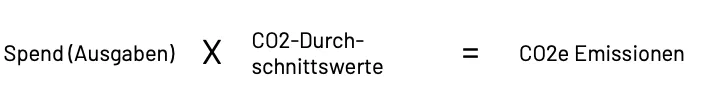
Spend-based / financial carbon accounting uses the average CO2e emissions per unit of financial expenditure in order to assign emissions a financial market value.
Activity-based
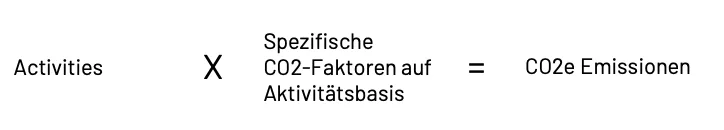
Activity-based / physical carbon accounting captures direct and indirect greenhouse gas emissions and takes into account all industrial activities and processes that affect the Earth’s atmosphere.
For this, the company’s raw data is recorded. The type of data collected depends on the specific activities, but usually includes energy consumption, fuel consumption, purchased goods, production volumes or logistics processes.
Telusio’s view
To ensure the most precise calculation of emissions possible, the activity-based approach should be preferred. Here, individual “activities” or processes, such as construction materials or operating supplies, are assigned a specific emission factor in order to quantify total emissions and enable the greatest possible transparency. One example would be the steel used in a larger machine. The material use of the purchased steel (“activity”) is multiplied by a specific emission factor, and a precise CO2e value can be calculated.
This decouples carbon accounting from possible price effects that can occur with the spend-based method. After all, an increase in the cost of steel, for example – and thus an increase in the “spend” factor for steel – by no means implies higher CO2e emissions.
Your customer is asking for a PCF?Let’s talk.
Discover the easiest way to audit-ready PCFs – AI-powered and expert-reviewed.
Book an initial call